
Driven by a relentless global boom in artificial intelligence stocks, relaxed post-crisis capital regulations, and surging lending demand from hedge funds, Wall Street’s premier investment banks are hurtling toward a historic financial milestone. Even with an entire quarter left to go in the fiscal year, major financial institutions have already locked in a banner year for their equities trading divisions, shattering previous performance records.
According to comprehensive company filings, the five largest U.S. investment banks have generated a staggering $67 billion in equities revenue through September 30. That impressive haul sits a full $7 billion higher than the total revenue generated by the entire group during the entirety of the previous year, which itself had stood as a record-breaking period for the industry.
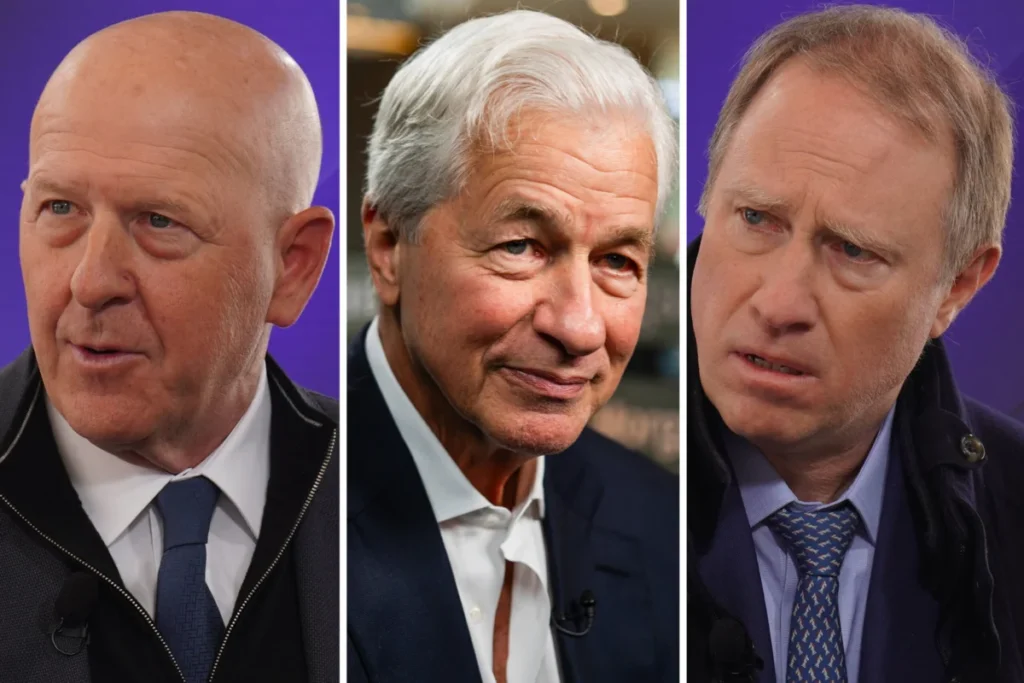
Yet, beneath those industry-wide figures lies a distinct concentration of power. Wall Street’s undisputed "Big Three"—Goldman Sachs, JPMorgan Chase, and Morgan Stanley—have successfully captured the lion’s share of what is rapidly crystallizing as the most lucrative arena in modern banking. Together, these three institutional powerhouses have raked in a combined $52 billion in stock trading revenue over the first three quarters of the year, accounting for nearly 80% of the entire sector’s total take.
"When it comes to the AI mega trade, the Big Three consider each other their main competitors, and that’s pretty much it," Mike Mayo, a prominent banking analyst at Wells Fargo, noted in an interview with CNBC. "They’ve been best positioned to take advantage of this market."
Across the financial district, major banking institutions are experiencing an extraordinary run of blockbuster profits. This upward trajectory has been propelled by a soaring overall stock market valuation, alongside surging trading activity from both institutional and retail investors across individual equities, exchange-traded funds, and complex derivatives. A major catalyst behind this heightened market engagement is the aggressive deployment of leverage. Through their prime brokerages, these mega-banks are extending substantial loans to hedge funds, enabling institutional investors to significantly amplify their market bets.
Prime brokerage—the specialized business of providing hedge funds with critical services such as margin loans, securities lending, and bespoke trading execution—has rapidly transformed into a vital competitive battleground and a primary engine of revenue growth. The prime brokerage operations housed within the Big Three are the beating heart of the broader equities narrative, maintaining deep relationships with the largest and most active funds operating across global markets and asset classes.
Bank executives reported that client demand for leverage to finance large-scale bets on AI hardware, cloud hyperscalers, and semiconductor supply chains has reached unprecedented heights. At Goldman Sachs, equities financing activities skyrocketed by 96% during the third quarter alone, hitting a record-breaking $3.37 billion. While competitors JPMorgan Chase and Morgan Stanley do not explicitly break out identical figures in their quarterly disclosures, executives from both firms acknowledged that they are navigating a remarkably similar operational dynamic.
"I like your ‘insatiable demand for capital’ point. That feels about right," JPMorgan Chief Financial Officer Jeremy Barnum remarked during the bank’s third-quarter earnings conference call, responding directly to analyst inquiries concerning the unrelenting market appetite for financing.
"In this moment where AI is such an overwhelming theme… there is capital being tapped through all kinds of different mechanisms," Barnum added, underlining how deeply structural the trend has become.
This extraordinary surge in demand has helped fundamentally reshape the equities trading desks at the Big Three. Once viewed as cyclical, purely transactional operations vulnerable to sudden market downturns, these desks have evolved into durable, high-margin lending engines that generate reliable, recurring revenue streams, according to veteran Wall Street executives.
At the same time, this structural shift has exacerbated a widening performance gap between Wall Street’s dominant elite and their traditional rivals, such as Bank of America and Citigroup, highlighting a stark bifurcation in the broader capital markets.
"For clients, the value isn’t just a price on one trade, it’s coverage and continuity," Rachid Alaoui, JPMorgan’s global head of equities, explained in an interview with CNBC. "You want a dealer that can give you the full suite across products, and you want that service to travel with you across regions. That matters in stressed markets and periods of volatility."
Executing multibillion-dollar transactions—such as complex leveraged swaps tied to volatile artificial intelligence stocks or broad sector exchange-traded funds—requires a massive, resilient balance sheet. According to trading executives, the industry’s largest institutions possess the capital depth required to absorb potential $100 million losses without jeopardizing their quarterly financial health. Smaller, more specialized, or regional banks simply cannot underwrite single-trade risks of that magnitude, forcing them to turn away profitable business or steadily cede valuable market share to the giants.
Furthermore, U.S. prime brokers have experienced a significant structural tailwind following the strategic retreat of several major European financial institutions, including Credit Suisse, from the equities and prime brokerage space, noted Herman Chan, an analyst at Bloomberg Intelligence.
"Prime is one of the ultimate scale businesses," Chan observed. "If you have a strong equities franchise, the hedge funds will want to transact with you because you have a bigger pool of trading opportunities with counterparties."
Picks and shovels
While domestic U.S. markets were heavily captivated by software and cloud computing giants throughout the year, trading executives emphasize that the fastest-growing geographical frontier for equities has been located across Asia.
Institutional investors have flooded into markets like South Korea and Taiwan, aggressively targeting the foundational "picks and shovels" providers of the global artificial intelligence supply chain. These include specialized memory chipmakers and semiconductor manufacturers whose advanced hardware is indispensable for the rapid construction of modern data centers, Alaoui pointed out.

For the Big Three, which maintain deep-rooted institutional footprints spanning Tokyo, Hong Kong, Seoul, and Mumbai, capturing the Asia trade proved to be a financial goldmine. However, trading executives quickly caveat that local transaction taxes and stamp duties are frequently bundled directly into top-line revenue reporting, which can artificially inflate Asian prime brokerage totals.
Industry observers also note that there is currently no universally standardized definition of what constitutes equities trading revenue. While some financial institutions incorporate auxiliary business lines like clearing services into their stock trading metrics, others deliberately exclude them, making precise, apples-to-apples comparisons across firms a complex exercise.
Yet, these accounting nuances do little to detract from the overwhelming momentum coursing through the business. The broader equities rally, which originally kicked off in October 2022 just weeks before OpenAI publicly released ChatGPT, continues to command investor attention.
"We’re still in a stock-based world," Morgan Stanley CEO Ted Pick asserted during his firm’s earnings conference call. "Equities are still, all things being equal, the attractive asset class."
Even as the chief executives of Goldman Sachs and Morgan Stanley maintain that the global artificial intelligence infrastructure build-up remains in its foundational, early years, financial analysts caution that any sign of AI failing to deliver on its transformative promises could leave these heavily exposed banks more vulnerable than their peers.
The unprecedented boom has also sparked broader regulatory and industry concerns regarding the systemic risks posed by heavily leveraged hedge funds.
The International Monetary Fund issued a formal warning cautioning that growing leverage, crowded market positions, and synchronized selling sprees among hedge funds could introduce severe financial stability risks. The IMF estimated that global hedge fund assets had swelled to an astonishing $13 trillion.
Back in August, JPMorgan CEO Jamie Dimon noted publicly that industrywide leverage was operating at "the highest it’s ever been," though he stopped short of characterizing the accumulation of risk as an immediate existential threat to global financial markets.
Wall Street executives and market analysts have been quick to point out that the financial system successfully absorbed the meltdown of several high-profile hedge funds over the summer without systemic disruption. While the collapse of the hedge fund managed by former OpenAI researcher Leopold Aschenbrenner captured widespread media attention, several smaller funds also experienced forced, disorderly unwinds.
Prime brokers, however, have grown increasingly adept at issuing rapid margin calls and swiftly shedding counterparty risk the moment market conditions turn against their clients, Alaoui explained.
"In the summer, some investors had positions they were forced to unwind," he told CNBC. "They deleveraged, risk came down, and the market moved on."
‘Known unknowns’
An additional catalyst fueling the historic equities boom is the regulatory environment fostered by Washington. Regulators operating under the administration have moved to ease specific post-crisis leverage rules for the largest U.S. banking institutions. These regulatory adjustments provide major banks with significantly more breathing room to expand balance sheet-intensive operations, including prime brokerage. Finalized in 2025, the revised rules permitted eligible banks to adopt the eased standards as early as January.
By dismantling stringent balance sheet caps that historically treated ultra-safe U.S. Treasury holdings and fully collateralized prime brokerage loans with the same punitive risk weightings as far riskier corporate assets, regulators have granted major dealers vastly greater operational flexibility to deploy balance sheet capital.
"Capital did go down, so you have to say the system is somewhat more levered because of the relaxation in regulations," said Darrell Duffie, a professor of finance at Stanford University and a recognized authority on systemic financial stability. "It’s not a good idea, but it hasn’t gotten dramatically out of whack."
While an expanded market size paired with elevated volatility naturally generates higher trading volumes, derivatives activity, and leverage, Duffie suggested that these developments are not inherently alarming on their own.
Wall Street executives similarly downplayed systemic anxieties surrounding leverage, emphasizing that sophisticated collateral management frameworks and frequent, rigorous stress-testing protocols allow them to identify and mitigate potential vulnerabilities long before they manifest into crises.
"Hedge fund leverage as a contributor of risk to the system is very much in the category of known unknowns," JPMorgan’s Barnum stated. "It doesn’t mean it’s riskless, but we kind of know what it is."