
Starbucks reported mixed quarterly financial results on Thursday, showcasing a tale of two distinct operational regions as its domestic turnaround continued to take firm hold while its international cafes underperformed market expectations during the final quarter of fiscal 2026.
The coffee giant’s performance in its home market easily topped Wall Street projections for the period ended September 27, demonstrating that CEO Brian Niccol’s strategic pivot is resonating with American consumers. However, weaker-than-anticipated results overseas and a cautious revenue outlook for the upcoming fiscal year caused shares of the company to fall nearly 2% in extended trading following the earnings announcement.
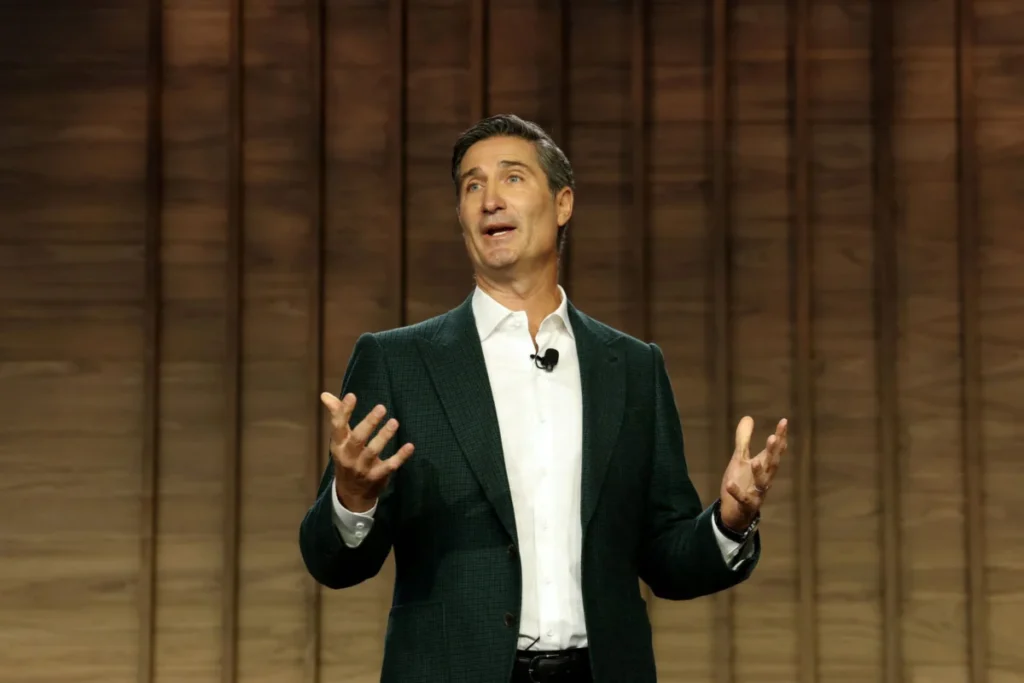
Despite the headwinds in international segments and a projected revenue dip for the next fiscal term, leadership struck an optimistic note regarding the broader trajectory of the global brand. "We enter fiscal 2027 with momentum, a clear set of priorities and higher ambitions for what Starbucks can become," CEO Brian Niccol said in a video shared widely on the company’s corporate website.
Speaking further during the company’s earnings conference call with analysts and investors, Niccol emphasized that Starbucks is currently running well ahead of schedule to meet the ambitious fiscal 2028 operational targets originally laid out during the company’s major investor day event in New York City back in January 2026.
For the fourth fiscal quarter of 2026, Starbucks reported net income attributable to the company of $677.2 million, or 59 cents per share, marking a significant recovery from the $133.1 million, or 12 cents per share, reported during the same period a year earlier. When excluding restructuring costs, impairment charges, and other one-off items, the company delivered an adjusted earnings per share of 80 cents. Net revenue for the quarter fell 4% to $9.14 billion, a decline primarily reflecting the complex structural effects of shifting its historically massive China business into a joint venture operating model.
Against this backdrop of corporate restructuring and strategic realignment, global same-store sales increased by a robust 7.2%, comfortably beating Wall Street estimates compiled by StreetAccount, which had projected a global increase of roughly 6%. This global comparable sales growth was heavily fueled by an increase in the average ticket size, while total transactions grew by 1.8% over the course of the quarter.
In the United States, cafes reported an even stronger performance with same-store sales growth hitting 7.7%, easily topping StreetAccount consensus estimates of a 6.5% increase. This domestic strength is directly tied to the implementation of Niccol’s signature "Back to Starbucks" strategy. Under this comprehensive initiative, the executive team has relentlessly focused on improving fundamental speed of service, making store environments more welcoming to lingering guests, and sharpening the precision of its marketing campaigns. These targeted operational changes have measurably helped the brand win back lapsed customers and deepen loyalty.
"Starbucks brand affinity is at near record levels as our menu innovation, marketing and merchandise continue to create moments that drive culture and bring people into our coffee houses," Niccol told analysts during the call.
The power of this menu innovation and cultural resonance was vividly demonstrated during the crucial autumn season. The company noted that its North American rollout of its perennial fall menu—anchored by the iconic and culturally ubiquitous pumpkin spice latte—marked the strongest autumn launch day in the history of the company. Furthermore, the company highlighted that matcha has officially achieved milestone status, now standing as a $1 billion product category for Starbucks globally.
The domestic turnaround was also physically manifested in the company’s retail footprint and capital improvements. By the end of the fiscal year, across the combined markets of the United States and Canada, Starbucks successfully completed more than 1,700 comprehensive cafe uplifts. These renovations are specifically designed to make stores warmer, more inviting, and better optimized for customer stays. Company data has consistently shown that locations receiving this makeover—which includes thoughtful tweaks like increased seating capacity and softer, more ambient lighting—experience noticeably higher transaction volumes in the aftermath.
These physical store investments occurred even as the company pruned underperforming assets. During the quarter, Starbucks opened 303 net new cafes globally. Concurrently, in line with announcements made in September regarding its broader retail optimization, the company moved forward with closing approximately 1% of its North American footprint, amounting to roughly 250 locations, as part of the rigorous structural turnaround.
While the domestic picture was undeniably bright, the company’s international operations encountered friction. Outside of North America, international comparable sales ticked up by just 0.9%, as traffic declines at storefronts largely offset a modest increase in the average ticket size. That international growth rate fell significantly short of analyst estimates, which had anticipated a 3.2% increase according to StreetAccount data.
In response to these regional variances, Starbucks has continued to evolve its global operating structure. Following the transition of its massive China business into a joint venture framework, the company has increasingly shifted the bulk of its broader international business toward a licensed model. This approach empowers experienced local operators to take operational charge of regional markets. Additionally, reports surfaced in September indicating that the coffee titan is exploring the potential sale of a majority stake in its established Japan business, according to sources cited by Reuters.
Looking ahead to fiscal 2027, Starbucks has provided Wall Street with a forecast that presents a complex mix of above-consensus earnings and below-consensus revenue growth. The company is projecting an adjusted earnings per share range of $3.15 to $3.25, which sits comfortably above the consensus Wall Street expectation of $3.14 per share.
However, the company’s anticipated revenue trajectory provoked a more cautious market reaction. Starbucks is projecting an anticipated net revenue decline of 1% for the upcoming fiscal year, a figure that is weaker than expected given that analysts were previously forecasting net sales growth of 1.4%. On the domestic front, the company remains confident, projecting North American same-store sales growth of 4% for the full fiscal year 2027.
According to CFO Cathy Smith, the comprehensive earnings and revenue outlook for the upcoming year accounts for several unique variables, including an additional operating week in the fiscal calendar and the ongoing financial effects of transitioning the China business model. Furthermore, Smith noted that the company is projecting slight deflation in overall green coffee prices alongside a deliberate slowing of net new North American cafe openings. Both of these operational factors will exert a temporary downward weight on full-year revenue numbers as the leadership team prioritizes quality, store profitability, and operational efficiency over sheer unit growth.